
Rent vs Buy: How to Find Your Break-Even Year
Rent vs buy explained: compare total ownership costs to rent, find your break-even year, and stress-test the answer with a free rent vs buy calculator.
Table of contents
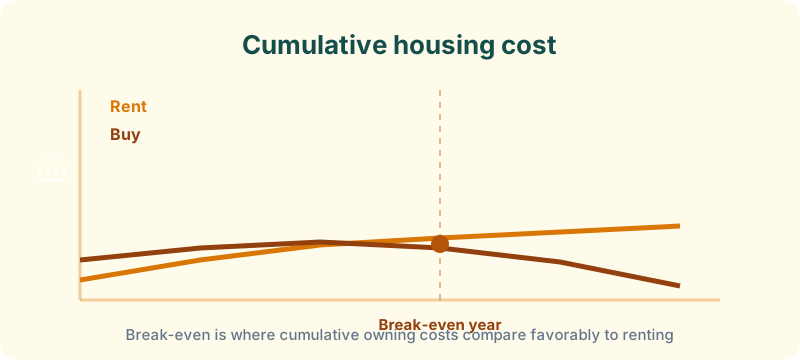
Your rent vs buy break-even year is the horizon where cumulative ownership costs (mortgage, taxes, insurance, maintenance, and transaction costs) may undercut the cost of renting—given your local numbers and how long you will stay. Renting is not “throwing money away,” and buying is not automatically building wealth.
Compare total costs over your expected stay, not mortgage payment versus rent alone. Use Budget Planner HQ’s free rent vs buy decision tool to stress-test scenarios, then confirm the monthly payment still fits in your budget planner before you offer or renew a lease.
Ownership costs more than the mortgage
Homeowners pay principal, interest, property taxes, homeowners insurance, maintenance, and transaction costs at buy and sell time. Comparing rent to mortgage payment alone tilts the math toward buying even when it isn’t cheaper.
Ongoing costs many first-time buyers underestimate:
- Maintenance and repairs: budget 1-2% of home value per year. Older homes run higher.
- Property taxes: vary widely by location and can rise after purchase
- owners association fees or body corporate fees: common in condos and planned communities
- Closing costs at purchase: often 2-5% of the purchase price
- Selling costs: agent commissions and transfer taxes when you exit
- Opportunity cost of the down payment: what that cash could have earned invested elsewhere
Renting has costs too (monthly rent, contents insurance, and no equity build-up), so a fair comparison totals both sides over the same number of years.
Housing cost data shows wide regional variation. National averages won’t match your neighborhood.
Inputs that change the answer
Before you decide, estimate:
- Monthly rent for a comparable home (same neighborhood, bedrooms, commute)
- Purchase price and down payment
- Mortgage rate and term (30-year fixed is common in some countries, but not universal)
- Annual local property tax and maintenance
- Years you plan to stay: critical for break-even
Run these through the rent vs buy decision tool . See our rent vs buy decision tool guide for input definitions.
Interpreting break-even years
Break-even is the approximate time before cumulative owning costs align favorably with renting, given your inputs. Shorter planned stays usually favor renting because closing costs and selling fees consume early equity.
If monthly own cost exceeds rent and strains your budget, don’t stretch. Housing should fit inside a broader plan built with the budget planner . A home you can’t afford to maintain becomes a liability, not an asset.
Worked example: $2,200 rent vs $380,000 purchase
Consider a comparable home where rent is $2,200/month and the purchase price is $380,000 with 10% down ($38,000), a 6.5% 30-year mortgage, $4,800 annual local property tax, $1,600 annual insurance, and 1.5% annual maintenance.
Approximate monthly ownership costs:
| Cost | Monthly estimate |
|---|---|
| Principal & interest | ~$2,150 |
| local property tax | $400 |
| Insurance | $133 |
| Maintenance (1.5%/yr) | $475 |
| Total monthly carry | ~$3,158 |
Monthly ownership exceeds rent by roughly $958 before accounting for closing costs (~$11,000-$19,000 upfront) and eventual selling expenses.
If you plan to stay 3 years, cumulative extra ownership cost plus transaction fees often exceeds any equity gained. Renting may be cheaper on pure cash-flow math. At 10+ years, appreciation and principal paydown can flip the result, but appreciation is not guaranteed. The tool models your specific inputs so you can stress-test both scenarios.
If renting wins for your timeline, invest the monthly difference toward other goals using the savings goal planner .
How to read rent vs buy calculator output
After you run the rent vs buy calculator , focus on three numbers:
- Break-even year: how long you must stay before owning is cheaper in total
- Net cost difference at your planned stay length (5, 7, or 10 years)
- Monthly cash-flow gap: owning minus renting each month
A positive monthly gap means owning costs more out of pocket even while equity builds. Many buyers accept a gap because they value stability or expect appreciation. Know the gap so you fund it deliberately rather than by cutting retirement or emergency savings.
Sensitivity testing: what moves break-even?
Small input changes shift results. Test these scenarios:
- Mortgage rate +1%: raises the monthly payment and usually pushes break-even later
- Rent growth +2%/year: makes renting more expensive over time, helping buyers
- Home appreciation 0% vs 3%: changes equity build-up, but never rely on appreciation alone
- Stay length minus 2 years: often flips the winner from buy to rent
Run at least a pessimistic and an optimistic case. If only the optimistic case favors buying, proceed with caution.
When renting makes sense
- You may relocate within three to five years
- Maintenance would stress cash flow
- You need flexibility for career or family changes
- Local prices imply ownership costs far above rent
- You’re still building an emergency fund or paying high-interest debt
When buying makes sense
- You plan to stay seven years or longer
- Local price-to-rent ratios favor ownership
- You value fixed housing costs and stability
- You have an emergency fund in place after the down payment and closing costs
- You would not otherwise save the equity you build through principal payments
Use the loan amortization calculator to see how much of each payment goes to principal versus interest in the early years.
When break-even analysis doesn’t apply
Rent-vs-buy calculators assume rational actors with stable plans. They struggle when:
- You qualify for substantial subsidies or special programs: down payment assistance changes upfront math.
- You renovate aggressively: sweat equity and improvement costs aren’t always captured.
- Tax benefits dominate your situation: mortgage interest deductibility depends on itemizing deductions, which many taxpayers no longer do under current standard deduction rules.
- You’re buying primarily for non-financial reasons: school districts, family proximity, or stability have value calculators can’t price.
Use break-even as one input alongside lifestyle needs and overall financial health.
Common mistakes in break-even analysis
- Using list price instead of actual offer price. Small price changes shift monthly costs and equity buildup.
- Ignoring rent growth. If rents rise 4% annually, the comparison changes over time.
- Assuming you’ll sell at peak value. Markets correct. Stress-test flat or modest appreciation.
- Forgetting cash reserves. Emptying savings for a down payment increases financial risk even if math favors buying.
- Treating break-even as a guarantee. It’s a model based on assumptions you control.
- Comparing rent to principal and interest only. Taxes, insurance, maintenance, and association fees change the math dramatically.
- Using national averages. Your local price-to-rent ratio matters more than national headlines.
Mini-FAQ
What is a good break-even year? Many buyers need 5-7+ years before owning beats renting on total cost. Shorter horizons often favor renting.
Should I include low-deposit mortgage insurance? Yes, if your down payment is under 20% on a conventional loan. low-deposit mortgage insurance adds to monthly ownership until you reach sufficient equity.
Does a bigger down payment always help? It lowers monthly costs and interest paid, but it also ties up cash that could earn returns elsewhere. The tool can model opportunity cost.
Is renting throwing money away? No. Rent buys shelter and flexibility. Ownership turns some cost into equity, but often only after years of higher total expenses.
Should I buy if my mortgage payment is lower than rent? Not automatically. A lower payment can still lose to rent once taxes, maintenance, and closing costs are included.
Can I rent and invest the difference? Yes. Many renters who invest consistently build wealth without owning. The comparison should include what renters do with savings.
What to do next
If buying looks viable on paper, save a larger down payment to reduce monthly costs and rerun the tool. If renting wins, redirect the housing-cost difference into savings or debt payoff. Before any offer, confirm your full housing payment fits within a sustainable budget. Our 50/30/20 budget guide helps set that ceiling.